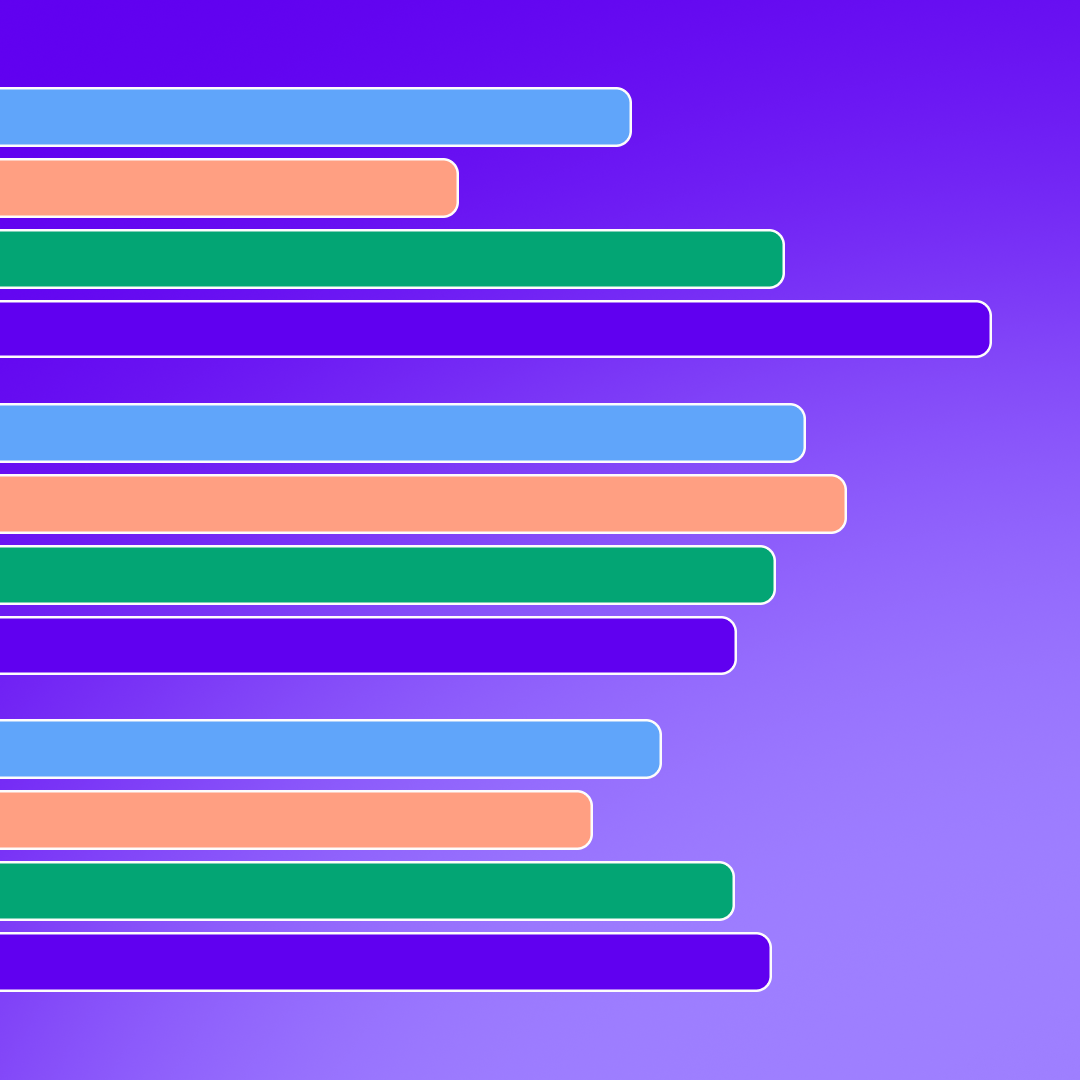
Percentage of contracts that are tail spend (by category)


What percentage of SaaS contracts are tail spend in 2026?
Tail spend gets less attention than headline "top vendor" spend, but it's often where the operational risk actually lives.
A small number of large vendors dominate most spend reporting. By contract count, the picture flips: a large volume of low-value contracts can make up the majority of total contracts while representing only a small share of total spend. That long tail is harder to govern and more prone to duplicate tools and shadow IT. It's also usually the least-negotiated part of the software budget, because no single contract looks big enough to justify real scrutiny.
After a broad-based improvement in Q2, Vertice's Q3 2026 data shows tail spend creeping back up. The average tail-spend share across categories rose from 63.4% to 65.4%, an increase of 2.0 percentage points. Tail spend grew as a share of contracts in 16 of the 17 categories tracked. The reversal is partial, not total. The average remains below Q1 2026's 68.5%, and most categories are still under their Q1 levels. But it's a reminder that consolidation gains don't hold on their own. In 14 of 17 categories, tail spend still accounts for the majority of contracts.
- The rebound is broad but mostly modest. Most categories rose by 1 to 3 points. Artificial Intelligence was essentially flat at 68.0%, and IT Infrastructure rose only half a point to 65.6%. This points to a gradual, market-wide drift back toward small, dispersed purchasing rather than a sharp reversal in any one area.
- CRM saw the biggest jump, though it remains the most consolidated category. CRM's tail-spend share rose 7.0 points, from 32.7% to 39.7%. That's a 21.4% relative increase, the largest of any category, and it takes CRM above its Q1 level of 37.4%. Even so, CRM still has the lowest tail-spend share of any category. CRM purchasing remains centralized around a small number of large, strategically negotiated platform contracts, but more smaller add-on tools appear to be accumulating around those core platforms.
- Monitoring is the only category that kept improving. Monitoring's tail-spend share fell a further 2.7 points to 44.7%, after a 9.0-point drop last quarter. That makes it one of only three categories where tail spend is a minority of contracts, alongside CRM and Productivity Suite (49.5%).
- Design and Development still carry the highest tail-spend burden. 84.5% of Design contracts and 81.3% of Development contracts are classified as tail spend, and both rose slightly this quarter. The vast majority of purchasing activity in these categories is still made up of small, dispersed contracts rather than centrally managed ones. This is likely where the least-negotiated, least-reviewed spend is concentrated.
Q3's rebound shows that tail spend doesn't stay down without ongoing oversight. Categories like Design and Development mean procurement and finance teams are managing a large volume of small, easy-to-miss contracts. Each one is a potential problem: a renewal that auto-renews unnoticed, a duplicate tool nobody flagged, or a deal signed at list price with no negotiation at all. Vertice brings this long tail of contracts under a single view through contract management and procurement orchestration. That way, even low-value purchases get proper visibility and approval rather than accumulating outside centralized oversight.
Data source: These insights are derived from over $75bn of global processed spend managed by Vertice in 2026.
Related insights
Join the community